Buyer
handbook
a home buyer's guide
Chris yeomans
lpt rEALTY
TABLE OF CONTENTS
1. preparing to buy
Getting Started
The home buying process
Real estate terms
FAQ's
7
8
9
10
2. Financials
Getting pre-approved
Pre-Approval Checklist
Financial Must Haves
Mortgage Loan Types
12
13
14
15
3. Finding your home
Buyer questionnaire
Picking the perfect home
The offer Process
17
18
20
4. Finals steps and closing
Final steps
Things to Avoid
Scheduling your move
What to bring to closing
22
23
24
25
Thank you!
As a real estate agent, I promise to work tirelessly to market and sell your home for the best possible price.
I'll keep you informed every step of the way and ensure that the selling process is as smooth and stress-free as possible.
Your satisfaction is my top priority and I'm committed to delivering outstanding service throughout the entire transaction.
chris yeomans
C: (407)927-1545
1210 Millenium Pkwy Ste.1050
Brandon Fl 33511
Chris@Yeomansgroup.com
@Chrisyeomans_realtor
meet our team
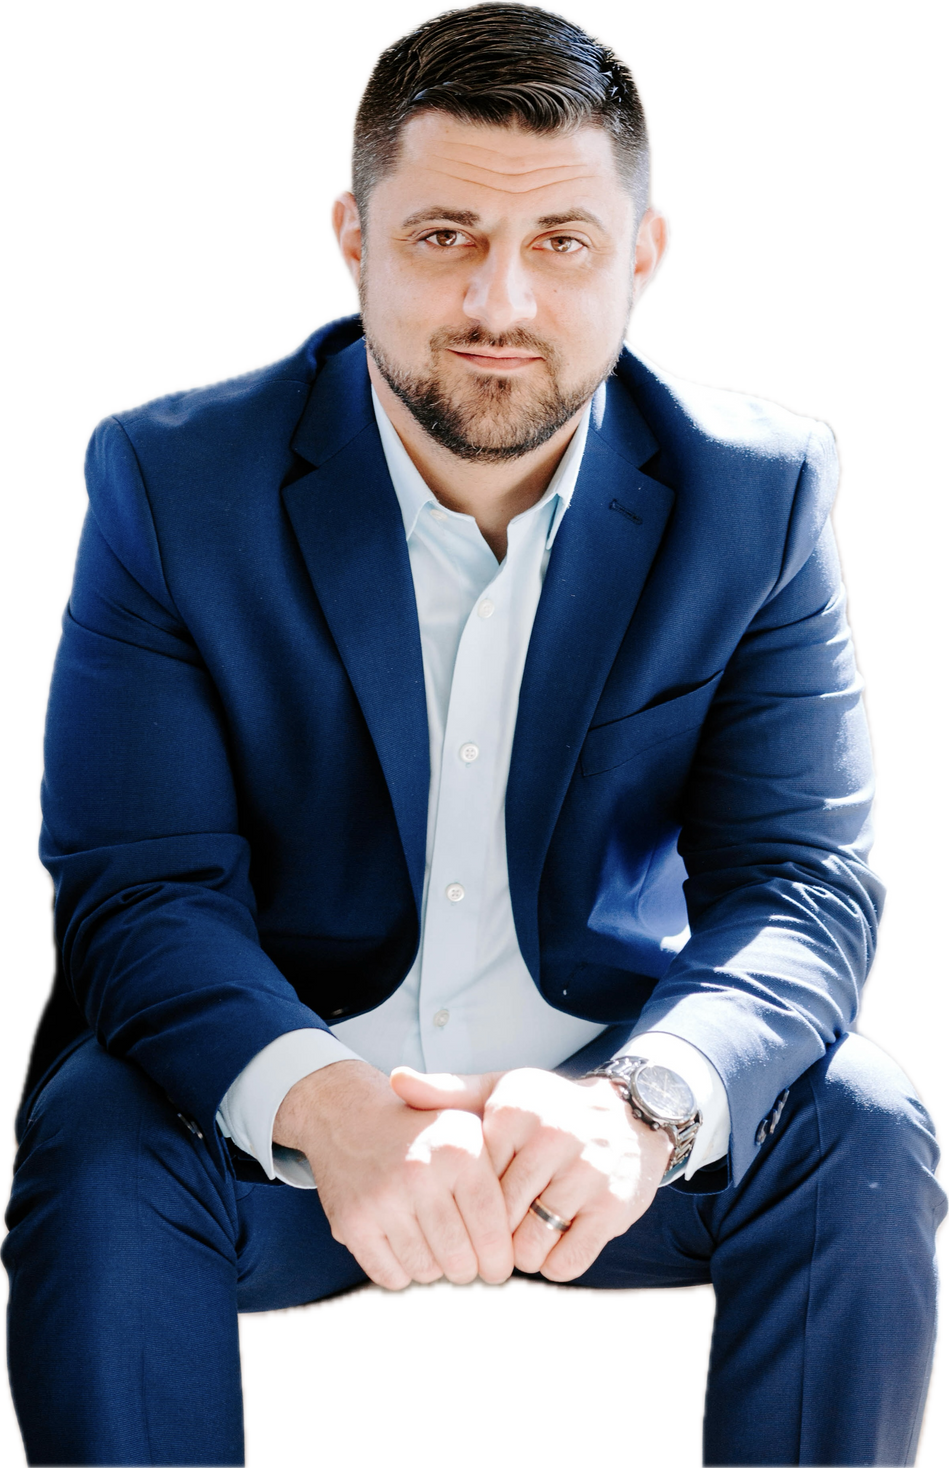
chris yeomans
Real Estate Agent
As a Florida native for over 30 years, Chris has intimate knowledge of the area and a strong desire to make his home, your home. With over 7 years of experience in the real estate industry and working alongside realtors from the title insurance side, Chris has a plethora of knowledge that he brings to the table to ensure your home buying or selling experience is seamless. His business is built on four core values: Communication, Commitment, Honesty, and Trust. His passion for helping others, combined with these four core values, have allowed him to assist his clients in securing their dream home.

preparing
to buy
getting Started
We start every home buying process with the proper research and preparation. Your checklist for this stage includes the following goals:
Determine the type of home you want
Determine where you want to live
Find a local real estate agent to help you

home buying process
4
3
1
2
Offer & Acceptance
Find your home
Meet with your agent
Get pre-approved
6
7
5
get your keys and move in!
Prepare for closing
order inspection & appraisal
home buyer
words you should know
closing costs
Taxes, insurance, and other lender expenses paid at the end of the transaction by the seller, buyer, or both.
down payment
Is what you typically pay up front for a house in order to close the sale. Usually 3-20% of the purchase price. Not the same as closing costs.
debt to income
DTI is the comparison of your monthly debt payments to your monthly income before taxes, expressed as a percentage.
Appraisal
Property and/or land valuation completed by an appraiser who determines the market value - typically 1-4 weeks.
Earnest money
Deposit made to a seller showing the buyer's good faith in a transaction. Typically 1-3% of purchase price.
closing
Usually a meeting that includes documents, signatures, checks, and everything needed to buy or sell the house.
title insurance
Insurance to protect the lender or owner from any claims related to the title of the property. Usually paid for by the buyer.
escrow
Funds deposited with a third party and held until a specific date is reached and/or a specific condition is met.
buyer faqs
what's the first step of the home buying process?
You'll need to get a mortgage unless you're paying cash for a house. To know how much home you can afford, you need to get pre-approved for a loan first.
How much money do I need for a down payment?
Usually 3-5% of the purchase price of the house.
How long does it take to buy a home?
Typically around 30 to 45 days after acceptance.
What other fees are there, besides the downpayment?
Mainly loan origination and closing costs at about 2% to 4% of the loan amount. You'll also have to pay for a home inspector, a home warranty, HOA fees, insurance, home maintenance and more.
Can I buy and sell my current one at the same time?
Absolutely! Depending on your situation, we'll recommend buying or selling first.
What kind of credit score do i need to buy a home?
A score of 620 or higher can get you better lending terms.
When can i expect to recieve the keys to the new house?
You'll get the keys to your new home on closing day once the transaction is complete and fully funded by the title company.
financials
$$$

getting pre-approved
A pre-approval letter in your hands can turn the home offers you make into irresistible invitations. So before you start looking for a home, getting your finances in order is crucial.
Like the first stage of the buying process, shopping for a loan and getting pre-approved are best done a month or two ahead of your home search. Sorting out your finances can take some time; more importantly, the application for mortgage pre-approval takes approximately 45 days.


Pre-approval checklist
Proof of income:
Provide documentation of your income, such as W-2 forms, tax returns, and pay stubs for the past two years.
employment verification:
Provide evidence of stable employment for at least two years, such as a letter from your employer or a verification of employment form.
credit history:
Your lender will check your credit report to evaluate your creditworthiness, so make sure you have a good credit score and a clean credit history.
assets:
You'll need to provide documentation of all your assets, such as bank statements, investment accounts, and retirement accounts.
debt obligations:
Provide documentation of all your current debt obligations, such as credit cards, car loans, and student loans.
down payment:
Determine the amount of your down payment and provide documentation of the source of funds for the down payment, such as bank statements or gift letters.
Pre-approval application:
Complete a pre-approval application with your lender, providing all the necessary information and documentation.
Property information:
Provide information on the property you intend to purchase, including the address, purchase price, and any other relevant details.
Financial must haves
down payment
Although you'll pay this at closing, proof of this is also what will help you secure your mortgage.
earnest money
When you make an offer on a home, you will be expected to pay a deposit as a show of good faith. It will be applied to your down payment or closing costs.
insurance
You may need to pay for mortgage insurance depending on your down payment and loan. You are required to purchase both Title Insurance and Homeowners Insurance.
closing fees
Be prepared to cover the cost of attorney fees, surveys, appraisals, and documentation.


Mortgage Loan types
Loan Type | who qualifies | down payment | upfront mortgage insurance | monthly mortgage insurance |
FHA Loans Federal Housing Administration | anyone who meets minimum credit and income levels | At least 3.5% of purchase price | 1.75% of loan amount | 0.07% of the principal balance for the life of the loan, if down payment was below 5% |
VA loans Department of Veteran Affairs | Current servicemembers veterans with honorable discharge some surviving spouses | NONE | 0 | 0 |
USDA loans U.S. Department of Agriculture | Anyone who meets minimum credit and income levels who is buying a home in a USDA designated area | 0 | 2% of the loan amount; can be rolled into mortgage | 0.03% of the remaining principal balance for the life of the loan, if down payment was 0 |
Conventional Mortgages | Anyone who meets the lender's credit, income, and debt level requirements | Varies from 3% to 20%, but typically ranges from 5% to 20% | 0 | If the down payment is less than 20% mortgage insurance runs as much as 0.21% of the loan each month |

finding
your home
Buyer Questionnaire
buyer name:
Address:
Phone:
email:
co-buyer name:
Phone:
Email:
Have you been pre-approved?
Yes
No
what's your price range?
Are you selling your current home?
Yes
No
Additional notes:
bathrooms:
bedrooms:
when do you need to move by?
area(s):
style of home:
sfh
townhouse
condo
Most important in a home:
deal breakers in a home:
Picking the perfect home
Before you look for a home, you should know the type of property you’re after. Is it a condo that meets your needs and preferences? Or is it a single-family home that fits your long-term goals?
To help you decide, consider the following factors:
How much you can afford
Age of the property
Take into consideration your annual income, monthly expenses, and debt-to-income ratio, all of which will affect the mortgage loan you can afford.
[City, State] real estate offers both historic homes and new construction. A resale property might be the one that you need with a few minor tweaks. But if you’re after a brand-new, move-in property, consider buying new construction.
non-negotiables
List down features that you absolutely need to have in your new house. Consider your proximity to your work and community services, nearby schools, home size and number of rooms. This will help you determine the type of property that meets your needs best.
Finding the right location
Consider the neighborhood
Proximity to work
Research the community where you plan to purchase a home. Look for features such as nearby schools, public transportation, shopping centers, parks, and entertainment options.
Consider the distance and ease of transportation to your workplace. Check traffic patterns, parking options, and commuting times.
Check the local market
Check property condition
Study the local real estate market to understand the property values, trends, and market conditions. Check the price of homes in the area to ensure that you are getting a fair deal.
Examine the condition of the house, including its age, construction quality, and necessary repairs. Have a home inspection to determine if there are any major defects or issues.
evaluate surroundings
consider accessibility
Take into account the property's surroundings, such as traffic noise, air pollution, and potential hazards. Consider the climate and weather patterns in the area.
Think about the accessibility of the property to other amenities, such as hospitals, police stations, fire stations, and airports.
Check the crime rate
determine property value
Research the crime rate in the neighborhood to ensure the safety of your family and property.
Assess the potential future value of the property based on location, surrounding developments, and community growth trends.
the offer process
once you submit an offer
We'll meet and review your offer together. Once the details are thoroughly reviewed and understood, the seller will have three options:
1 - accept the offer as written
2 - decline the offer
If they feel the offer isn't close enough to their expectations to further negotiate this offer.
3 - counter offer
If they agree to most the offer but want to change a few details, they can counter our offer with the new terms.
You can negotiate back and forth as many times as needed until you reach an agreement or someone chooses to walk away.
Once an offer is accepted by both parties, you are officially under contract.

final steps &
closing
Final steps
order the Inspection
Ordering inspections before closing when buying a home is crucial to avoid potential complications and ensure the home is in good condition. General and pest inspections should be completed, and any issues should be addressed before finalizing the sale.
order the Appraisal
Ordering an appraisal for buyers before closing on a home can be a good idea to ensure that the home is priced correctly and to avoid any surprises during the sale process. However, it is not always necessary and the decision should be made based on individual circumstances.
finalize loan application
You'll submit all necessary documents, such as income verification and credit reports, to the lender. The lender will then review the application and make a decision on whether to approve the loan. Once approved, you'll sign the loan documents and provide a down payment before the loan can be funded and the home purchase can be completed.
negotiate final offer
When negotiating a final offer for a property, it's crucial to consider current market and property conditions, urgency of the sale, and be realistic with expectations to come up with a fair and reasonable offer. Flexibility and compromise are key to reaching a mutually beneficial agreement with potential buyers.
Things to Avoid After Applying for a Mortgage
Don't change bank accounts.
Don't apply for new credit or close any credit accounts.
Don't co-sign other loans for anyone.
Don't make any large purchases
Don't deposit cash into your bank accounts before speaking with your bank or lender.
Consistency is the name of the game after applying for a mortgage. Be sure to discuss any changes in income, assets, or credit with your lender, so you don't jeopardize your application.
The best plan is to fully disclose and discuss your intentions with your lender before you do anything financial in nature.
after signing
Start by decluttering and packing up your belongings and donate or throw away anything you don't need, create an inventory of anything valuable that you plan to move, and, finally, you'll want to get estimates from moving companies for your specific needs.
scheduling your move
4 weeks to move
- Schedule movers/moving truck
- Buy/find packing materials
- Start packing
2 weeks to move
- We will schedule you a time to close and sign your documents
- Contact utility companies (water, electric, cable)
- Change address: mailing, subscriptions, etc.
- Minimize grocery shopping
- Keep on packing
3 weeks to move
- Your lender will arrange appraisal
- Title work will be completed
- Keep packing
1 week to move
- You will complete your final walkthrough
- Finish packing
- Clean
- Pack essentials for a few nights in new home
- Confirm delivery date with the moving company.
what to bring to closing
a photo id
a cashier's check
the closing disclosure
proof of insurance
your real estate agent
our promise to you
Choosing us as your real estate team means you'll have a dedicated and experienced team working to help you sell your property for the best price. We provide personalized service, expert advice, and a commitment to your satisfaction.
Honesty and transparency
Communication and responsiveness
Professionalism and expertise
Diligence and attention to detail

Success stories
I highly recommend this real estate team! Their expertise and professionalism made the process of selling a property effortless. They were responsive, knowledgeable, and went above and beyond to ensure a smooth transaction. I couldn't have asked for a better team to work with.
-kevin w.
Chris was incredibly helpful throughout the entire home selling process. He was knowledgeable, communicative, and always had my best interests in mind. I couldn't have asked for a better experience and would highly recommend his services to anyone in need of a reliable and trustworthy agent.
-jason m.
Overall, I had an exceptional experience, and I would highly recommend their services to anyone seeking a reliable and trustworthy agent.
-michael f.
Congratulations!
chris yeomans
C: (407)927-1545
1210 Millenium Pkwy Ste. 1050
Brandon Fl 33511
Chris@Yeomansgroup.com
@Chrisyeomans_realtor